Flexible Work, Fragile Coverage
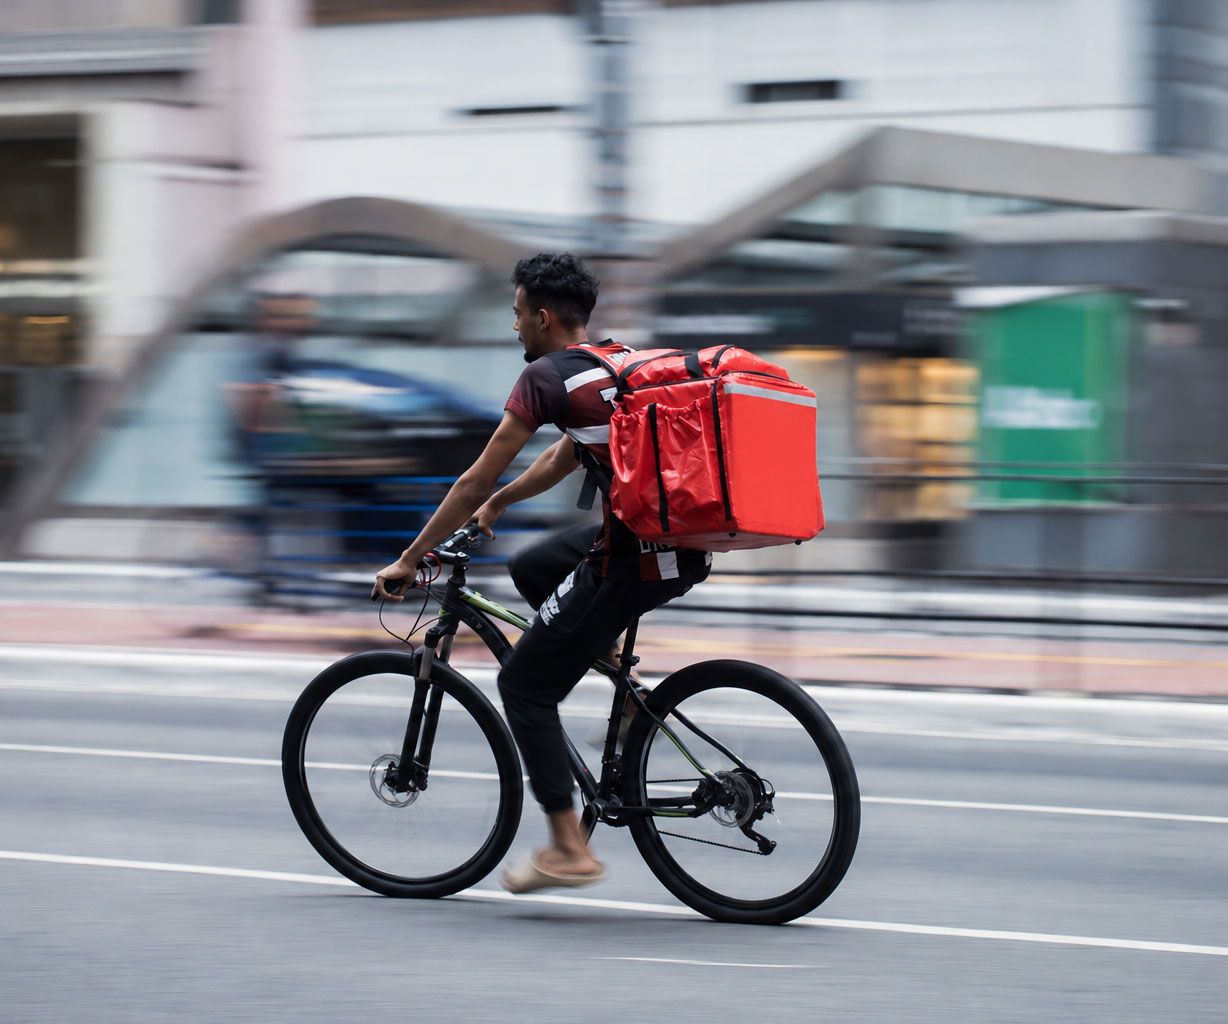
Independent work is no longer a side story in the American economy. Millions of Americans work as independent contractors. Add in the drivers, couriers, freelancers, consultants, and creators who treat gig income as a supplement, and the number climbs further.
What often gets overlooked is that gig work typically doesn't include traditional employer-sponsored benefits. That means no group health plan, no employer paying part of the premium, and no HR department to call in October for enrollment.
The numbers back this up. KFF (formerly the Kaiser Family Foundation) research shows that about one in five workers isn't offered coverage through their job, a number that nearly doubles for lower-wage workers. For all of them, the individual health insurance marketplace isn't a backup plan. It's the only plan.
The Real Problem Is Not Access. It Is Income That Moves.
Most gig workers can find a plan. What trips them up is that coverage decisions assume you know what you will earn this year, and gig income is rarely that predictable.
A strong quarter followed by a slow one can change what you qualify for. Marketplace subsidies are based on estimated annual income, and if your estimate is off, the difference gets settled at tax time. If you guess too low, you may owe money back. If you guess too high, you pay more each month than you need to.
This is a point not to be ignored. The enhanced subsidy provisions that were in place for several years through the ACA Marketplace expired at the end of 2025, which changed the math for many people compared to previous years. If you shopped for coverage two or three years ago and assumed nothing had shifted, now is a good time to revisit it.
Where Independent Workers Usually Start
There is no one right answer here, and the best fit depends on your income, your health, which state you live in, and your family situation. Broadly, these are the paths people look at:
- ACA Marketplace plans, which cover essential health benefits and cannot turn you down for a pre-existing condition
- Coverage through a spouse's or partner's employer plan, often the most economical option when it is available
- Medicaid or CHIP, depending on your income and which state you live in
- Private individual plans outside the ACA marketplace, which may suit higher earners who do not qualify for subsidies
- Association or professional group plans available through some trade organizations
Be careful with plans marketed as cheap alternatives to major medical insurance. Some do not cover pre-existing conditions and can leave significant gaps in your coverage. If you take regular prescriptions or have any health history, read the fine print closely or have someone help read through it with you.
"Extras" That Many Gig Workers Forget
When you take a nontraditional work path, you're not just missing the primary health plan, but everything else that was bundled with it.
That usually includes dental, vision, disability coverage, and often a life insurance policy. For someone whose income depends on being physically able to work, disability protection can matter as much as the health plan does. A delivery driver with a broken wrist has no sick leave to fall back on.
Supplemental or ancillary products are worth a close look for exactly this reason. Accident, hospital indemnity, and critical illness coverage can help with the costs a high-deductible plan leaves behind. They are not a substitute for major medical coverage, but an important supplement to fill the gaps and soften a bad time.
Practical Habits That Help
- Track your income monthly so your annual estimate stays close to reality
- Contact us for help reporting income changes to the Marketplace during the year instead of waiting until you file
- Treat premiums as a fixed business expense, not something you cover with whatever is left over
- Ask about the self-employed health insurance deduction when you talk with your tax preparer
- Know that losing other coverage or a major life change can open a special enrollment window to change your medical insurance plan
Do Not Sort This Out Alone
Open enrollment for individual coverage generally opens in early November, which makes September and October the right time to review what you have. Comparing plans on your own is possible. Doing it well, with variable income and supplemental options in the mix, takes some experience. That's where we come in. Our brokers can compare options across carriers, help you build a realistic income estimate, and point out gaps you might not think to ask about. There is no cost to you for that conversation.
If you work for yourself and you think it's time to review your coverage, reach out to our office. We are here to help you figure out what fits.